


EU CBAM: Responsibilities, Costs and Support
The EU Carbon Border Adjustment Mechanism (CBAM) places a carbon cost on certain goods imported into the European Union.
The definitive regime began on 1 January 2026. In-scope imports during 2026 can therefore create a financial liability, although the certificates covering those imports will be purchased and surrendered in 2027.
For UK businesses supplying European customers, particularly on Delivered Duty Paid (DDP) terms, this cost needs to be considered when agreeing selling prices and customer arrangements.
Which goods are affected?
CBAM covers specified commodity codes within six sectors:
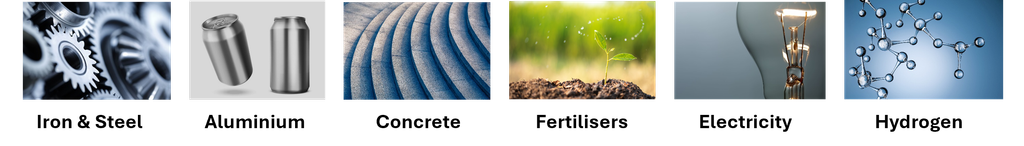
The commodity code determines whether a product is covered. Not every product within these sectors falls within scope.
A 50-tonne annual exemption applies to the combined net mass of relevant CBAM goods imported by each importer across the calendar year. This is a cumulative allowance, not a separate allowance for each shipment or supplier. Electricity and hydrogen are excluded from this exemption.
Who is responsible?
The authorised CBAM declarant is responsible for the annual declaration and associated certificate obligations. This may be the EU importer or its indirect customs representative.
Where a UK business acts as the importer without an EU establishment, an EU-established indirect customs representative must be appointed to fulfil the relevant obligations on behalf of the UK business.
DDP terms alone do not establish who holds the statutory responsibility. Before shipping, the parties should be clear on:
- Who will act as the authorised CBAM declarant
- Who will obtain and provide the required emissions information
- Who will pay the certificate costs and associated service charges
Agreeing these points early helps avoid unexpected costs and clearance difficulties.
Key dates and what it means:
- 1 January 2026 – The definitive regime began. In-scope imports can create a CBAM financial liability.
- February 2027 – Certificate purchases begin to cover 2026 imports.
- 30 September 2027 – The first annual declaration and corresponding certificate surrender are due, covering 2026 imports.
The payment date may be in 2027, but businesses should assess and budget for their exposure now.
Default values or actual emissions?
For most covered goods, there are two main approaches to calculating embedded emissions.
Default values
These are values established by the European Commission. Applicable mark-ups can increase the calculated emissions and may result in a higher cost than using verified actual data. Using the relevant default values does not require separate verification of the producer’s actual emissions.
Actual emissions
This approach uses emissions data from the installation producing the goods. The data must meet the CBAM methodology and be independently verified by an appropriately accredited verifier.
Businesses considering actual emissions should engage with their suppliers early. Suitable data and verification need to be arranged in time for the annual declaration.
What determines the cost?
The calculation depends on the commodity code, quantity imported, country of production, applicable production route and embedded emissions.
It also takes account of relevant EU free allocation adjustments and any eligible carbon price already paid in the country of origin.
There is no single percentage that can reliably be applied to the shipment value. The calculation needs to reflect the goods and circumstances involved.
Published Certificate Prices
CBAM certificate prices are linked to the EU Emissions Trading System. The following prices have been published for 2026 imports:
Import period Price per certificate (€ per tonne of CO₂ equivalent)
January – March 2026 €75.36
April – June 2026 €75.28
July – September 2026 €82.32
These prices apply to embedded emissions, not tonnes of freight. The final cost depends on the emissions calculation and applicable adjustments.
The fourth-quarter price is scheduled for publication in January 2027. From 2027, certificate pricing moves from quarterly to weekly prices.
See the European Commission’s certificate pricing page for updates.
How Simarco can help
We can coordinate specialist support through our French partner to prepare indicative CBAM certificate cost estimates.
Assessments use the available product information, import volumes and relevant emissions assumptions. Estimates are subject to the accuracy and completeness of the information supplied and may differ from the final liability.
Charges may apply for this service. The scope and commercial terms will be agreed before work begins.
To discuss your requirements, contact CBAM@Simarco.com
Information and prices reviewed: November 2026. Further guidance is available on the European Commission’s CBAM website.